The inspection report lands in your inbox, the buyer’s agent attaches a list, and suddenly you are weighing inspection repair request seller options you hoped you would never have to think about: fix it, credit it, cut the price, or politely say no.
Take a breath. A repair request is not an accusation and it is not an ultimatum, even when it reads like one. It is the start of a short negotiation, and the buyer on the other side usually wants the same thing you do, which is a closing that actually happens. What you need for your inspection repair request seller options is a clear way to sort the list, price each item honestly, and pick a response that protects your net proceeds and your calendar.
This guide walks through the four main responses, how each one changes what you keep and how fast you close, and the facts that should make you switch from one to another. It is general education written for home sellers, and it stays neutral on agents, attorneys, buyers and sale channels. Your contract and your state’s rules decide what is actually allowed, so we point you to where to check rather than guess.
If you want the bigger picture first, our cornerstone guide on home sale contingencies from the seller’s side explains how the inspection period fits with appraisal and financing deadlines.

Key takeaways
- Read your contract first. The inspection clause sets the buyer’s rights, the deadlines and what happens if you stay silent, so it shapes every one of your inspection repair request seller options.
- Sort the list into three piles. Safety and function items, cosmetic or preference items, and maintenance notes deserve very different responses.
- Compare in net dollars and days. A repair, a credit and a price reduction can look similar on paper and still leave you with different cash, risk and timing.
- A counter beats a flat no. Saying no entirely is allowed in many contracts, but it often reopens the buyer’s right to walk, so decide with that exit in mind.
- Document everything. Quotes, receipts, permits and written agreements protect you when the buyer, lender or appraiser asks questions later.
- Not legal or tax advice. Rules vary by state and contract, so confirm the details with your agent, attorney or title company.
Define your goal before weighing any inspection repair request seller options
Before you look at a single line item, decide what a good outcome means for you among your inspection repair request seller options. Sellers often answer the list one repair at a time and only later notice that the pile of small concessions added up to more than a clean price cut would have cost. Starting from the goal, and not from the buyer’s list, keeps you from negotiating item by item without a destination.
Goal, timeline, cash, condition and risk tolerance
Five questions drive almost every decision about inspection repair request seller options, and it helps to answer them in writing before you reply to anyone. What is the most important result: the highest net, the fastest closing, or the least hassle? How firm is your move-out date? How much cash can you spend before closing without straining your next purchase? What condition is the house really in? And how would you feel if this buyer walked away tomorrow?
The last question matters more than people admit. A seller with a backup offer and a flexible timeline can afford to hold firm. A seller who has already signed a contract on the next home, has a rate lock expiring, or has a mortgage payment squeezing them each month has far less room to gamble on a standoff. Neither person is right or wrong. They simply face different math, and the same buyer request deserves different answers.
Evidence to gather: contract clause, report, quotes and payoff figures
Pull together the actual documents, not your memory of them. You need the signed purchase contract with every addendum, the full inspection report with photographs, the buyer’s written repair request or amendment, and any specialist reports that came with it. Add your payoff statement and an honest estimate of closing costs so you know what the sale is currently expected to net.
Then read the inspection clause slowly. Look for the number of days the buyer has to deliver a request, the number of days you have to respond, and what the contract says happens if you do not respond. Some forms treat silence as refusal, others as acceptance, and some leave it open. Whether the buyer can terminate, ask again or simply proceed depends on that wording, which is why the clause is the first thing to check among your inspection repair request seller options.
Next, get real numbers. Ask two licensed contractors for written estimates on the items that look expensive or unusual, and keep the quotes. Estimates beat guesses in a negotiation because they let you say, calmly, “here is what my contractor says this costs,” instead of arguing about adjectives. Our guide on the inspection contingency from the seller’s side covers how the inspection window itself works.
A scenario, an exception and your next step
Picture a seller we will call Dana, with an ILLUSTRATIVE contract at a round price of $400,000. The buyer asks for fourteen items. Dana’s goal is a closing before her new job starts in five weeks, she has no backup offer, and she has limited savings. Her priorities are speed and certainty, which points toward a short, focused counter rather than a long fight over every outlet cover and loose handrail.
Now change one fact. Suppose Dana had two backup offers in hand. Her leverage would be much stronger, and a firmer response would carry less risk. The exception is worth remembering: the best answer is never universal, it depends on how much you can afford to lose if the buyer leaves.
Your next step in weighing inspection repair request seller options is simple. Write down your goal in one sentence, your hard deadline, and the most cash you are willing to commit. Keep that note beside the buyer’s list while you work through the rest of this article. It will stop you from making a quick promise you regret later.
Facts that could change the decision
Some details can flip an answer completely, and sellers often discover them late. It is far better to surface them now, while you still have time to choose, than to learn about them from an appraiser, lender or the buyer’s attorney after you have already agreed to a plan.
Evidence to gather: age, permits, disclosures and financing type
Start with what you already told the buyer. If your seller disclosure said the roof was original or that a past leak existed, a related inspection finding is not a surprise, and a buyer who read the form may bargain less aggressively. If the disclosure was silent and the inspector found something you knew about, the situation changes, because concealment can create legal exposure. Our guide to material defects in a seller disclosure explains why accurate paperwork protects you.
Check permits and age next. Work done without a permit, an old electrical panel, or an aging water heater can draw attention from lenders and insurers. Ask your local building department how to look up permits for your address, and ask your agent or attorney how unpermitted work is typically handled in your area, since practices differ widely from one place to another.
Finally, find out how the buyer is paying. Some loan programs set minimum condition standards that an appraiser must verify, such as safe handrails, working systems and a sound roof, and a house that fails may need repairs before the loan can close. In that case the repair is not really a negotiating point at all. It is a condition of the buyer’s financing, and credits may not satisfy it. Ask the buyer’s lender, through the agents, which standards apply.
One federal rule is also worth remembering. If your house was built before 1978, federal law requires lead-based paint disclosure, and you can read the details in the EPA real estate disclosure guidance. Any inspection finding about peeling paint on an older home deserves a careful, documented response.
A scenario, an exception and your next step
Imagine an inspector flags a cracked chimney crown and an old gas furnace with a rusted heat exchanger. Your instinct might be to offer a modest credit. But if the furnace is a safety item and the buyer’s lender or insurer will not accept it, the credit does not solve the real problem. The exception is that safety and lender-driven items often have to be fixed or formally resolved, even when you would prefer to pay cash.
Your next step with these inspection repair request seller options is to ask three questions in writing through the agents: which items does the buyer’s lender require, which items does the buyer’s insurer care about, and which are simply wishes? The answers sort the list faster than any opinion, and they turn a vague complaint into a specific plan you can price.
While you wait for replies, keep your tone steady. Buyers often write requests in a long, anxious burst after reading a thick report, and many are open to a calm counter once they see that you are taking the findings seriously. A short, courteous reply that promises a considered answer by a stated date buys you time and goodwill.
Compare the four realistic inspection repair request seller options side by side
There are really four inspection repair request seller options when a buyer’s list arrives. You can make the repairs yourself, offer a credit at closing, lower the purchase price, or decline some or all of the requests. Many real inspection repair request seller options blend them, such as fixing two safety items, crediting one expensive item and declining the cosmetic rest. It still helps to understand each pure form first.
The table below puts the main routes next to each other on the points sellers care about most: what happens to your net proceeds, how much time the route takes, how it interacts with contingencies, how much work lands on you, and how likely it is to go sideways. The figures are directional, not promises, because every contract and market differs.
| Route | Effect on net proceeds | Time and contingencies | Seller workload | Execution risk |
|---|---|---|---|---|
| Complete repairs before closing | You pay contractor costs up front; cost can be lower or higher than a credit | Adds days or weeks; may need re-inspection or receipts | High: hire, schedule, supervise, document | Quality disputes, delays, permit questions |
| Closing credit | Fixed amount comes off your proceeds at the table | Fast; lender must allow the credit | Low: one written amendment | Lender limits; buyer may fix poorly or not at all |
| Price reduction | Lowers the contract price; can affect appraisal fit | Fast; may change loan size and cash needs | Low: amendment and updated figures | Buyer’s down payment and loan math may shift |
| Decline all requests | Protects proceeds if the buyer stays | Fastest if accepted; may reopen buyer’s exit | Lowest in the short run | Buyer may terminate or re-trade; deposit rules apply |
| Partial counter (mix of the above) | You choose where to spend and where to hold | Moderate; one more round of paper | Moderate | Lower than a flat no, if the counter feels fair |
Use the matrix of inspection repair request seller options as a checklist of questions, not a scorecard. Read across a row and ask whether you could live with the worst entry in it. A repair route that wins on cost can still lose if you cannot afford a three-week delay, and a flat refusal that wins on proceeds can still lose if the buyer has an easy way out.

Option one: make the repairs yourself before closing
Of all the inspection repair request seller options, doing the work gives you control over who fixes the problem, how it is fixed and what it costs, and it can make the house more appealing to a nervous buyer. It also puts the schedule and the quality risk on you, which many sellers underestimate.
Evidence to gather: licensed quotes, permits and a paper trail
If you choose repairs, hire licensed, insured professionals for anything involving the roof, electrical, plumbing, gas, structure or heating and cooling. Get a written scope of work, the contractor’s license details where your state requires them, and a promise to provide receipts and any warranty paperwork. Ask whether the job needs a permit, because a repair finished without one can create a new problem that appears in a later inspection.
Keep every receipt, photo and invoice in one folder. Many contracts expect the seller to show that agreed repairs were completed in a professional manner, and some buyers ask for a re-inspection of the fixed items before closing. A neat file answers those requests in minutes. If a title company or lender asks about the work later, you already have the answer.
Compare the contractor’s quote with what a credit would cost. For ILLUSTRATIVE numbers, suppose a repair quote is $3,000. A credit of that amount costs you the same cash, but a repair also costs you your time, and a credit lets the buyer choose their own contractor. A repair can still be cheaper if you have a handy relative, a warranty, or a vendor you trust, though you should be careful about informal work that the buyer’s side may not accept.
Also think about the seller’s own mortgage servicer and homeowner’s insurance if the repair involves an insurance claim. A claim, even a small one, can follow the property in insurer databases, so ask your agent or insurance professional how to handle that before filing anything just to fund a repair.
A scenario, an exception and your next step
Consider a seller whose inspection found a leaking exterior hose bib and a water heater strapped incorrectly. Both are cheap, quick and obviously real. Fixing them in a single afternoon, with receipts, tells the buyer you are reasonable and closes the issue with almost no negotiating. The exception is when the problem is larger than it looks, such as a slow leak that has already damaged framing. Then a quick patch can backfire, and a specialist’s written opinion is worth paying for first.
Another exception is time. If your closing date is two weeks away and the only qualified roofer has a six-week backlog, repairing may be unrealistic however good the idea sounds. In that case a credit or a price reduction may serve everyone better.
Your next step among the inspection repair request seller options: for each item you are willing to repair, write down who will do it, the date it will be finished, and what proof you will hand over. Put those details into the written response, so the buyer is agreeing to a specific plan and not to a vague promise. Vague promises are where repair disputes at the final walk-through usually begin.
Option two: a credit, a price reduction or a polite no
The other three inspection repair request seller options share a feature: you stay out of the contractor business. They differ in how the money moves and in how the buyer’s lender sees it, so it is worth separating them clearly instead of treating “give them some money” as one idea.
Evidence to gather: lender credit limits, appraisal fit and contract wording
A closing credit is a sum the seller gives the buyer at closing, shown on the settlement documents. Lenders often limit how much seller credit a loan can include, and the limit depends on the loan program and the down payment. Ask the buyer’s agent to confirm in writing that the lender will accept the credit amount, or you may agree to something that cannot close as written.
A price reduction works differently. It lowers the contract price itself, which can change the buyer’s loan amount and down payment, and it may interact with the appraisal. If the appraisal already comes in near the contract price, a reduction can help; if the appraisal comes in low, a reduction may simply be the first step in a larger conversation. Our guide on what to do about a low appraisal covers that second situation.
Declining the request is the third path. It is usually permitted when the inspection clause lets the seller decide, but the contract may then give the buyer a defined window to accept the property as is or end the deal. Read the exact wording of what happens after a refusal. For the broader repair-versus-credit comparison across the whole sale, see repair credit versus seller repair.
Whichever of the inspection repair request seller options you choose, get it in writing. An email thread alone can be ambiguous, and a signed amendment with the exact dollar figure and the exact items removes doubt. Your title or escrow company will also need the final numbers to build your closing statement, which you can preview in our guide to the seller closing statement.
A scenario, an exception and your next step
Suppose the buyer asks for a $6,000 roof repair on an ILLUSTRATIVE $350,000 sale. You could offer a $2,500 credit, a $2,500 price reduction, or ask a roofer for a repair estimate. The credit and the reduction cost you the same cash today, but they land differently on the settlement statement and may affect the buyer’s loan paperwork differently. A buyer who plans to replace the roof anyway may prefer cash and the freedom to choose a contractor.
The exception is the buyer who truly cannot close without a repaired roof because the lender or insurer insists. Then neither a credit nor a reduction removes the barrier, and you will need to repair, or agree on a documented repair-by-closing plan with escrow holding funds, if your local practice allows that.
Your next step for these inspection repair request seller options is to draft two versions of your reply, one with a credit and one with a reduction, and ask the buyer’s agent which fits the loan better. A five-minute question can prevent a failed closing, and it signals that you are trying to solve the problem together.
Use a net-result decision rule to choose among inspection repair request seller options
Once you know the inspection repair request seller options, you need a way to choose without letting emotion or irritation make the call. The simplest rule is also the most useful: compare every response by what you will keep, how many days it adds, and how likely it is to hold together until the closing table. Cost, time and risk, in that order of dollars.
The rule works because it forces all inspection repair request seller options into the same units. A repair that costs $2,000 and delays closing by ten days is not directly comparable with a $2,500 credit that adds no days, until you decide what ten days is worth to you. Some sellers pay a carrying cost of hundreds of dollars a week in mortgage interest, taxes and utilities, and some are paying double housing costs. Others have almost none. Put your own number on it.
A price, time, cost and risk framework you can finish in an evening
Here is a framework for ranking inspection repair request seller options in plain steps. First, list each item the buyer requested. Second, assign it to a pile: lender or safety required, real defect, or cosmetic and preference. Third, price every item with a quote or an honest range. Fourth, decide a response for each pile, then add up the cash and the days. Fifth, set a walk-away line, meaning the most you will concede before you would rather relist.
Evidence to gather: the numbers that make the comparison honest
Three kinds of numbers keep any comparison of inspection repair request seller options honest. The first is the repair or credit cost for each item, supported by quotes. The second is your weekly carrying cost, which you can pull from your mortgage statement, tax bill, insurance premium and utility bills. The third is a realistic estimate of what a failed deal would cost: the days on market you would lose, the possible price pressure after a cancelled contract, and the price you might accept from a replacement buyer.
That last number is the hardest and the most important. A listing that returns to the market after a cancelled contract can raise questions in buyers’ minds, and an inspection report may follow the house in the form of required disclosures, since many states ask sellers to share known defects. Talk with your agent or attorney about what you would have to disclose to the next buyer if this deal fails. Our guide on what to do when a deal falls through after inspection goes deeper on that path.
Then do the arithmetic with ILLUSTRATIVE round numbers. Suppose the buyer’s list totals $9,000 in estimated work, of which $4,000 are lender-required safety items, $3,500 are genuine defects and $1,500 are cosmetic wishes. Responding with full repairs of the safety items, a $1,500 credit toward the defects and a polite no on the cosmetics would put your cost around $5,500 or less, depending on actual repair prices. That is a simplified example, not a prediction, but it shows how piles change the total.
Compare that with the alternative of refusing everything. You keep $9,000 on paper, but if the buyer walks and you relist for four more weeks at a $900 weekly carrying cost, you may spend $3,600 just waiting, plus the risk of a lower price. That does not mean concessions always win. It means the real comparison includes the cost of the deal failing.

A scenario, an exception and your next step
Take a seller with a strong market, where inspection repair request seller options lean toward firmness, and a backup offer. Her weekly cost is small, the backup is real, and the buyer’s list is long and cosmetic. Applying the framework to her inspection repair request seller options, she responds with two safety repairs and a courteous refusal of the rest. If the first buyer leaves, the backup steps in with little lost. The framework gave her permission to hold firm because the cost of failure was low.
Now take a seller with no backup, a rate lock on his next home expiring in three weeks, and a list that includes one costly structural note. His walk-away line sits much higher, because a failed deal could cost him the lock. The exception to every firm stance is a calendar that punishes delay.
Your next step in comparing inspection repair request seller options is to build a one-page sheet: items, piles, costs, days, and your walk-away line. Share it with your agent or attorney, ask what they would change, and keep the final version beside your signed amendment.
When new evidence should change your plan
Your first answer among the inspection repair request seller options is not a vow. Inspections often start a chain of follow-up opinions, and any of them can move the right response. The mistake is to stay loyal to an early position when the facts have shifted underneath it.
Evidence to gather: specialist reports, appraisal results and lender notes
Specialist reports are the most common trigger. A general inspector might write “recommend evaluation by a licensed engineer” next to a foundation crack, and the engineer might then conclude that the crack is cosmetic, or that it needs repair. Either result changes your list. If the engineer says it is cosmetic, the buyer’s request may shrink or disappear. If the engineer recommends work, you now have a real price and can negotiate from it.
Appraisal results are another trigger. An appraiser can note condition issues, and a low value can push the conversation back to price. If you already gave a credit, ask how it interacts with the appraised value. Likewise, a lender’s underwriting notes may reveal a requirement nobody mentioned during the first round, such as a safety correction on a deck or handrail.
Insurance can also move the plan. A buyer who cannot obtain homeowner’s coverage because of a roof’s age or an old panel may suddenly need repairs or replacement, even if the first request skipped them. Ask the buyer’s agent early whether insurance quotes have been obtained. Our cornerstone guide on seller contingencies explains how these deadlines stack up and why one delay can ripple through the rest.
Keep a simple log of each new document, the date it arrived and what changed. If a dispute arises, a dated log shows that you responded promptly and in good faith, and it is far easier to share than trying to reconstruct a month of text messages.

A scenario, an exception and your next step
Imagine you offered a $4,000 credit toward an electrical panel the inspector disliked. A week later, a licensed electrician examines it and says the panel is safe with a small, inexpensive adjustment. The new evidence suggests your credit may have been too generous. Depending on the contract, you may be able to revisit the amount if the amendment is not yet signed, but once signed, an amendment generally binds both sides, so slow down before you sign.
The opposite can happen. A plumber’s camera scan shows a collapsed sewer line, and now the stakes are far higher than the first list suggested. In that case, rethink the response, talk to your agent or attorney quickly, and consider whether the new facts need to be disclosed or whether the buyer is entitled to renegotiate under your contract.
Your next step with your inspection repair request seller options: set a calendar reminder for every deadline in the inspection clause, and treat each new report as a reason to re-run your one-page sheet. Reopening a spreadsheet costs nothing, while signing the wrong amendment can cost thousands.
A related issue is the reconsideration of value, where the buyer or lender asks an appraiser to look again after a low result. We explain that process in our guide to a reconsideration of value from the seller’s side, which pairs naturally with this article when condition findings and appraisal results arrive in the same week.
Real situations rarely match a textbook, so here is a second table that maps common seller situations to the inspection repair request seller options that tend to fit them. Treat it as a conversation starter with your agent or attorney, not a ruling. The last column is the part to focus on, because a single changed fact can reverse the answer.
| Situation | Route favored | Reason | Trade-off | Fact that changes the choice |
|---|---|---|---|---|
| Strong demand and a ready backup offer | Partial counter or firm no on cosmetics | Cost of the buyer leaving is low | Buyer may feel unheard and walk | Backup offer falls through or weakens |
| Firm move date and next purchase already under contract | Credit or reduction | Speed and certainty matter most | You give up more proceeds | Lender caps seller credits |
| Lender or insurer requires a safety fix | Repair with receipts | A credit may not satisfy the lender | Time and contractor risk | Contractor cannot finish before closing |
| Report flags a possible major defect | Specialist opinion first, then decide | Real cost is unknown until evaluated | Delay while you wait for the report | Specialist finds a serious problem |
| Older home sold as-is with a long cosmetic list | Decline cosmetics, offer to discuss safety | Age-related wear is expected | Buyer may re-trade price | Contract limits as-is language |
| Tight appraisal margin | Repair rather than reduce price | A lower price can worsen the value gap | Out-of-pocket cost up front | Appraisal already comes in strong |
To use the table, find the row closest to your own case, read across to the trade-off, and then check the last column against your real facts. If your facts match the last column more than the first, you probably belong on a different row. Bring both the table of inspection repair request seller options and your one-page sheet to your agent or attorney, and ask them to challenge your choice.
Quick scenario
A seller receives a list with twenty items. Eighteen are small maintenance notes, one is a loose deck railing and one is a questionable water heater flue. She repairs the railing and the flue with receipts, declines the maintenance notes in a friendly paragraph, and attaches the receipts. The buyer accepts. Her total cost is small, her closing date holds, and nobody argued about the loose cabinet knob. Your case may differ, and your contract controls the inspection repair request seller options available.
Tone matters as much as numbers when you present inspection repair request seller options. A reply that starts with thanks, acknowledges the safety items and offers a specific plan lands very differently from a one-line refusal. Buyers in the middle of a purchase are usually anxious, and they often respond better to a seller who sounds practical than to one who sounds defensive.
If you want a simple structure, try three short paragraphs. The first thanks the buyer and confirms you reviewed the report. The second lists the items you will fix or credit and the dates. The third lists the items you are declining and a one-sentence reason, such as normal age-related wear, with an offer to discuss anything the buyer feels strongly about. Short, specific and polite is a hard combination to argue with.
Counter-offers deserve the same care when you mix inspection repair request seller options. If the buyer’s request was large, you may want to trade across categories, giving a little on repairs in exchange for a firm closing date or a shortened contingency window. Our guide on counteroffer strategy for sellers covers how to structure those trades without losing track of what you have already conceded.

One more caution about fairness and honesty. Respond to every buyer’s request using the same standards, and never let a buyer’s background, family or any protected characteristic influence your response. Federal fair housing rules apply to the whole transaction, and the HUD fair housing resources explain them in plain language. Equally, do not hide a known problem to win a smoother negotiation, because your disclosure duties continue throughout the sale.
For a wider look at how repairs fit into the whole sale, you can also read our guide to repairs and selling as is, and our contingencies, inspections and appraisals section for the neighboring topics.
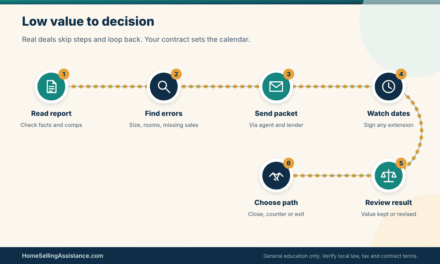
It helps to see how the inspection repair request seller options play out over the actual days of a contract, because the calendar is where most mistakes happen. On day one after the report arrives, do nothing except read, sort and ask questions. Resist the urge to reply the same evening. A reply written in a hurry tends to concede too much or sound too sharp, and either one is hard to take back.
On days two and three, collect quotes and ask the buyer’s agent which items matter to the lender and insurer. By day four or five, you should be able to describe each of your inspection repair request seller options in dollars and days. Many contracts allow only a handful of days for a response, so do not assume you have a week unless you have read the clause. If you need more time, ask for a short written extension rather than letting the deadline pass quietly.
Sellers sometimes ask whether they should handle the reply personally or let their agent do it. There is no single right answer. An experienced agent has seen how buyers react to different tones and can often hear what a buyer really wants beneath an aggressive list. A seller handling the sale without an agent carries that role alone and should be extra careful about deadlines and wording. Either way, the decision about your inspection repair request seller options belongs to you, since it is your money and your house.
Another common mistake is treating the inspection report as a verdict on the house. Inspectors are paid to find and describe every issue they can, including small ones, and a thick report is normal even for a well-kept home. Buyers who have never read one can feel alarmed by pages of photographs and cautious language. A calm explanation, backed by a contractor’s opinion, often reduces a scary-sounding finding to a modest job.
Likewise, when reviewing inspection repair request seller options, avoid the opposite error of dismissing every note as nitpicking. Inspectors do find genuine hazards: active leaks, unsafe wiring, missing safety devices, failing flues, and drainage that sends water toward the foundation. When you recognize a real problem and say so plainly, you earn credibility for the items you decline. Credibility is a quiet asset in negotiation, and it costs nothing to build.
Think too about what your repairs and concessions say about your inspection repair request seller options and the next steps. A buyer who sees quick, documented fixes tends to relax about everything else. A buyer who sees stalling tends to ask for more. If you decide on a credit, make the amount specific and explain how you arrived at it, using the quotes you gathered. A number with a source behind it is easier to accept than a round figure that appears from nowhere, and it reduces the temptation for the buyer to counter your counter.
Be careful with phrases like “as is” in this setting. Selling a home as is generally tells buyers you will not make repairs, but it does not erase disclosure duties, and it does not necessarily remove a buyer’s right to cancel during an inspection window. The wording of the contract and your state’s rules decide what an as-is sale actually means. Our cornerstone guide on home sale contingencies and the cluster pages on the seller’s view of contingencies explain how those protections interact.
Money mechanics deserve one more look, since inspection repair request seller options often differ most at the closing table. A repair paid before closing leaves your proceeds untouched on the settlement statement, though your bank balance already took the hit. A credit appears as a line item and reduces proceeds directly. A price reduction lowers the number from which commissions, transfer charges and other price-based items may be calculated in your area. Because those details vary, ask your title or escrow officer to run a draft statement for each version before you sign.
Consider also the question of who bears the risk if the work is imperfect. When you hire the contractor, a poor repair is your problem until the buyer accepts it at the walk-through. When you give a credit, the buyer chooses the contractor and owns the outcome. Some sellers like that clean break and are willing to pay a little more for it. Others prefer to keep control because they have a trusted professional. Both preferences are reasonable, and neither one is a sign of weakness or of being difficult.
Finally, keep an eye on the relationship between your response and the rest of your timeline. If you are also buying, a delay here can affect your own contingencies and your rate lock. If you are relocating, the order of events may matter for work or school. If you are selling an inherited or co-owned property, all owners may need to agree on any concession, which can take days. Mapping those dependencies early keeps your inspection repair request seller options realistic.
If you ever feel stuck, return to the simple question that began this article: what do you want from this sale, and what are you willing to give up to protect it? Whichever of the inspection repair request seller options you choose, you will make a better decision with your own numbers, your contract in front of you, and a friendly professional to check your reasoning. For anything involving a dispute, a possible legal claim or a large sum, a short consultation with a local real estate attorney is often worth the fee.
Frequently asked questions about inspection repair request seller options
Do I have to agree to anything on the buyer’s repair request?
Usually not, but it depends on your contract. Many contracts let the seller accept, counter or decline, and the buyer then decides whether to proceed, negotiate or end the deal within a defined window. Read the inspection clause and confirm the consequences of refusing with your agent or attorney. Your inspection repair request seller options are largely defined by that wording.
What happens if I ignore the request?
The outcome depends on the contract language and local custom. Some forms treat silence as a refusal, some as acceptance and some leave the question open, and deadlines may run while you wait. Silence can also cost you goodwill. Respond in writing before the deadline, even if the response is only that you need a few more days.
Is a credit better than doing the repair myself?
Neither is always better. A credit is quick and gives the buyer control, while a repair lets you control quality and sometimes cost. Lenders may limit credits, and some safety items may need to be fixed before the loan can close. Compare both against your timeline and your carrying costs.
Should I lower the price instead of giving a credit?
A price reduction changes the contract price, which can affect the loan amount and the appraisal comparison. A credit leaves the price alone and shows up as a line on the settlement statement. Ask the buyer’s agent which structure fits the buyer’s loan, and run both through your net proceeds estimate.
Can I say no to everything?
In many contracts you can, but the buyer may then have the right to terminate or proceed as is, depending on the clause. If you have strong demand or a backup offer, a firm answer can be reasonable. If you do not, weigh the cost of relisting before you choose it.
How do I know whether the repair estimates are fair?
Get at least two written quotes from licensed professionals for the expensive items, and compare scope as well as price. Beware of a single quote that comes from the buyer’s side with no supporting detail. A neutral, written scope of work is the best basis for a discussion.
Do I need to disclose the inspection findings to the next buyer if this deal fails?
Disclosure rules vary by state, and many states require sellers to disclose known material defects regardless of how they learned about them. A buyer’s inspection report may therefore matter later. Ask your agent, attorney or the state real estate commission what applies to you.
Should I hire a lawyer for a repair request?
Many sellers handle repair requests with an experienced agent, and some states routinely involve attorneys in every sale. Consider a lawyer if the findings are serious, if there is a dispute about what the contract allows, or if money is at stake that you cannot afford to lose. This is not legal advice.
What if the buyer keeps asking for more after we agree?
Once you sign an amendment, new requests generally need your agreement unless the contract provides another right. Review the signed paper, remind the buyer’s agent of the agreed terms in writing, and ask your agent or attorney how to respond if the buyer insists. Do not sign a second concession under time pressure.
Do repairs affect my taxes?
Repair costs and credits can interact with your taxable gain in ways that depend on your situation, and the rules are technical. The IRS explains the basics in its publication on selling your home. Ask a tax professional before assuming any particular treatment.
Before you reply to the list
A good answer to a repair list is specific, polite and tied to your real numbers. Sort the items, price them, check what the lender and your contract allow, and choose among your inspection repair request seller options with your walk-away line already written down. This article is general education, not legal, tax or financial advice, so confirm the details with your agent, attorney or title company before you sign anything.